The first question any advisor will ask you is not what yield you expect. It is: what do you own?
A token that appears to represent Spanish real estate can be any of five legal objects — a DLT-registered security, an SPV equity share, a participative loan, an accounting unit, or a cooperative housing right. Each produces a different tax treatment, a different succession mechanism, a different exit option, and a different risk profile. The marketing pages of the platforms that sell them describe the yield. None of them describe the wrapper.
This manual closes that gap.
🎯 What This Manual Solves
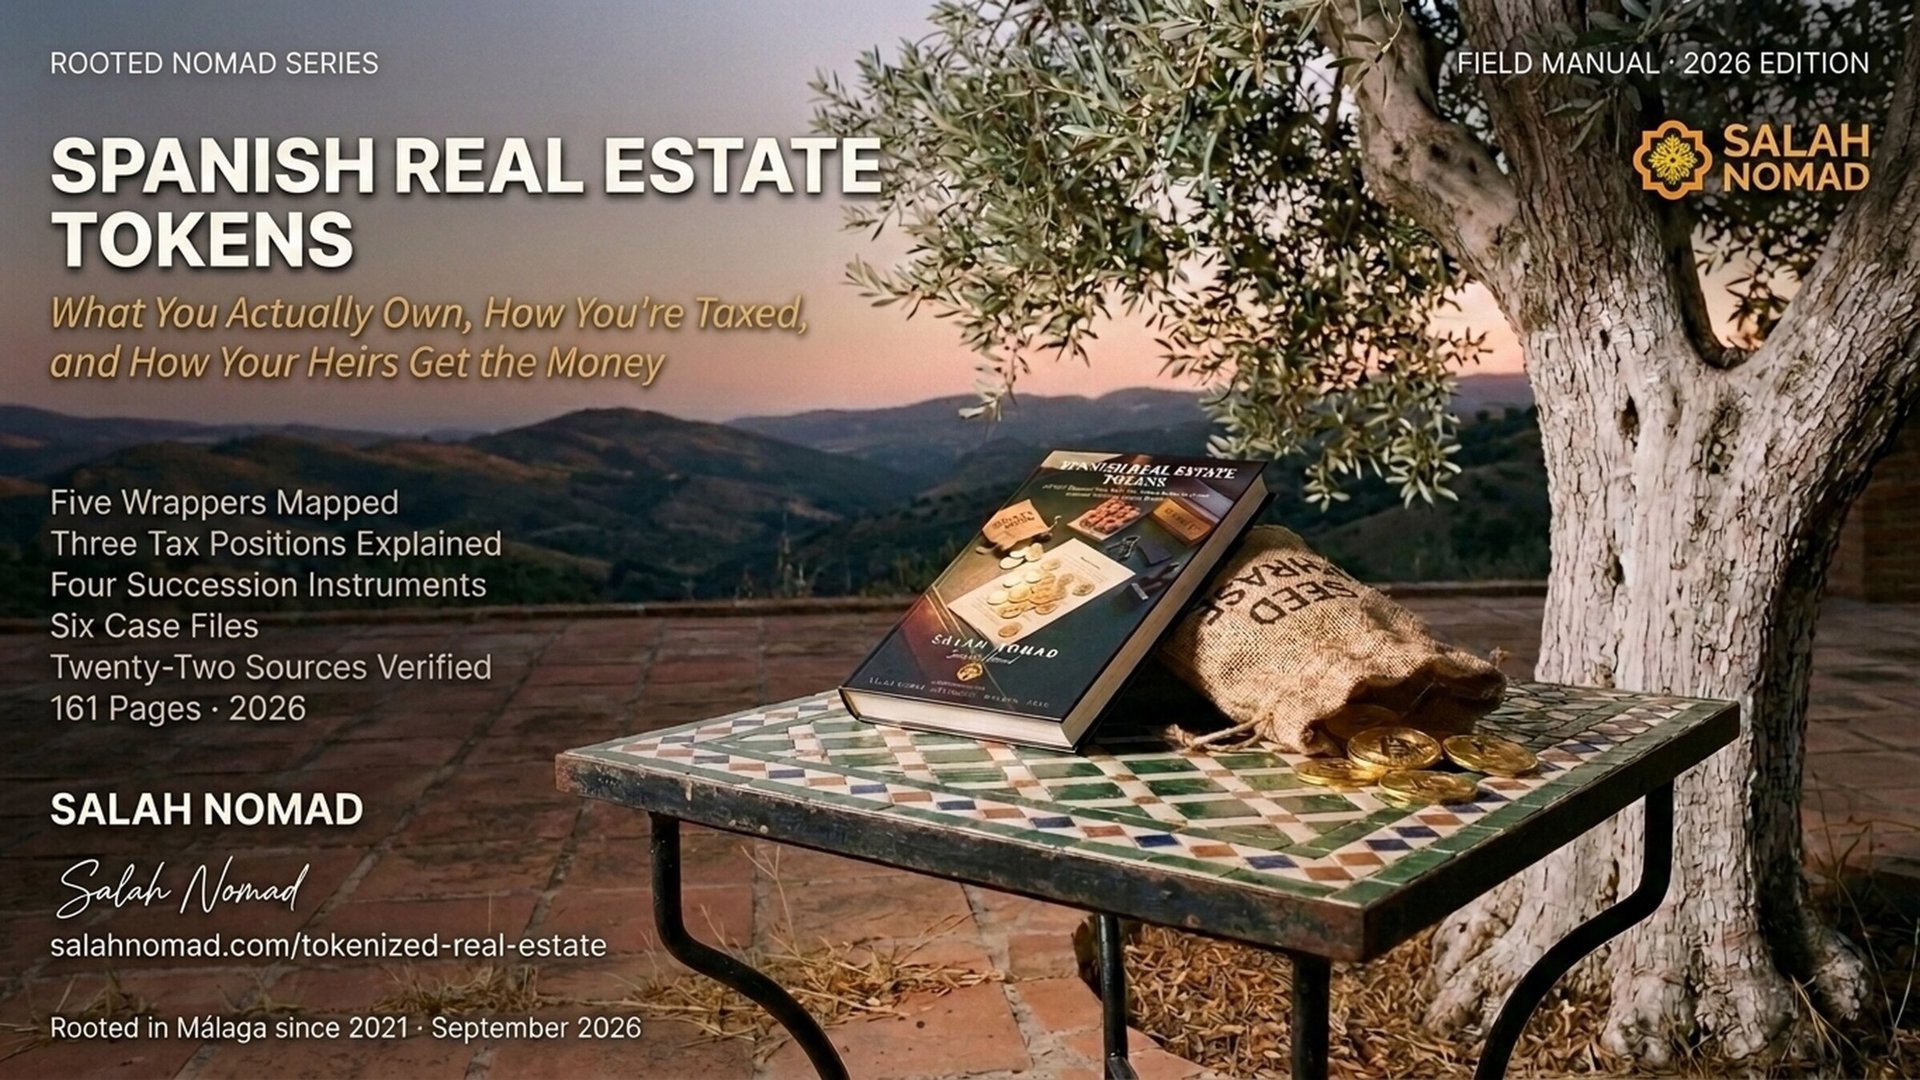
The five wrappers, decoded. DLT-registered security (Arca Habitatum, via CNMV ERIR), SPV equity (Reental), participative loan (Equito), accounting unit (Domoblock), cooperative housing right. Each wrapper explained through structure, issuer, tax treatment, succession mechanism, and exit option.
The tax classification the DGT has not resolved. Modelo 721 vs Modelo 720 — the three defensible positions a Spanish-resident holder can take, with the evidentiary memo each position requires.
The buyback reality, platform by platform. Equito: 3% commission, €2,000 per-user cap, discretionary frequency. Reental: P2P only, no guarantee, ~€60,000/month secondary volume. Domoblock: no documented procedure. Aurema: US LLC operating agreement.
The succession gap nobody documents. Why a tokenized position fails at the notarial deed. The DLT-registered alternative that works — and why no retail platform in Spain offers it yet. Légitimas applied to tokens. The professio juris election under EU Regulation 650/2012.
The liquidity trap, quantified. The European secondary market for tokenized real estate totals under €50,000 per day. The exit discount runs 3% to 15% depending on position size. The heir forced to sell to pay ISD pays the market’s price.
Six case files with exact numbers. The €12,000 position needing six buyback windows. The €180,000 inheritance sold at a 12% discount. The €16,400 penalty for the minimalist filing position. The 4-month DLT-registered succession. The unstructured succession that cost €14,000 and remains unresolved.
Two notarial instruments that close the gap. The Spanish will with the inventory clause, the acta de manifestaciones that reconciles the platform designation with the légitimas, the executor briefing that eliminates the discovery phase.
📘 Inside the Manual
Inside This Codex — 24 Chapters
The correction that matters: MiCA does not apply to real estate tokens
Why the marketing page answers a question you did not ask
Participative loan, SPV equity, DLT security, accounting unit, cooperative right
What "CNMV-regulated" does and does not mean
Seven questions before signing, four documents to demand
What happens when the wrapper is tested
The classification the DGT has not resolved
Capital mobiliario or capital inmobiliario — the deduction gap
The block matching rule applied to tokenized positions
Conservative, intermediate, minimalist — with risk profiles
€0 filing and €16,400 penalty on the same wrapper
The four structural gaps at the platform
The only wrapper that survives the platform
The constitutional floor no beneficiary designation escapes
The ISD liability versus the exit discount
The will, the acta, the professio juris election
Nine months versus eleven, and one unresolved
Under €50,000 per day, all platforms, all Europe
Four platforms, four different exit regimes
Six options, their costs, their conditions
14% discount vs 3-year hold, side by side
30 terms · 22 sources with verification dates
❓ Questions Readers Ask Before Buying
Is this legal or tax advice?
Does MiCA govern Spanish real estate tokens?
Which wrapper should I choose?
Does the manual cover the 2026 platforms?
Why 161 pages for a book on one asset class?
What is the DLT-registered wrapper and why does it matter?
How is this different from the free content on law firm blogs?
📂 Reads Well With
Before You Land — the pre-arrival manual for crypto holders crossing the Spanish threshold.
The Crypto Inheritance Framework — the légitimas, professio juris, and notarial mechanics extended to the full estate.
The Source of Funds Dossier — the forensic seven-layer file for proving crypto origins to a notary or bank.
The Crypto Holder’s Bank Playbook — the fiat rails that crypto-funded acquisitions ultimately pass through.
The companion volume
Before You Land prepares your crypto for the Spanish threshold. Spanish Real Estate Tokens protects what you own once you have crossed.
A note from the medina I am a publisher, not a lawyer, not a fiscal advisor, not a real estate agent. Nothing on this site is legal, fiscal, or investment advice. Verify every wrapper, every tax classification, and every succession mechanism with a qualified professional before committing capital. That is not a legal sentence I hide behind. It is the philosophy, repeated one more time.
“The harbour master does not fear the ship with clean papers.”
— Salah Nomad
Comments