B2B Field Manual · Revised October 2026
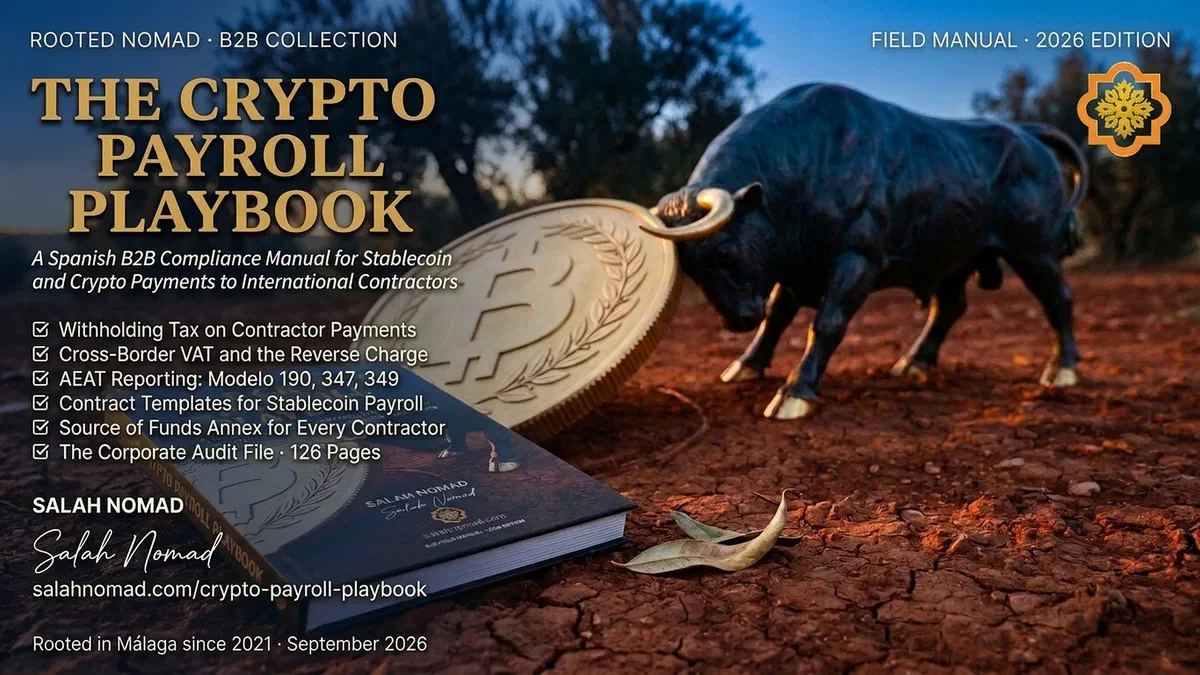
The Crypto Payroll Playbook
A Spanish B2B Compliance Manual for Stablecoin and Crypto Payments to International Contractors
The Crypto Payroll Playbook is a 126-page B2B compliance manual for Spanish SLs paying contractors in stablecoins and crypto. It covers withholding tax on crypto contractor payments, cross-border VAT and the reverse charge, five AEAT reporting models, and the three contract templates with SOF annexes. Written for CFOs, DAFs, and finance leads at Spanish companies, with three case files and four appendices.
- Length
- 126 Pages
- Revised
- Oct 2026
- Format
- Delivery
- Instant link
Why this manual exists
A Spanish sociedad limitada pays a contractor in USDC. The invoice states USDC. The accounting entry states euros. The Modelo 190 will state euros. Three documents, two currencies, one operation. This manual closes the gap between the rail and the classification.
What this guide solves
The rail is not the operation. The tax system classifies the service contract, not the payment method. A USDC transfer and a SEPA transfer produce the same corporate tax obligation — what changes is the computation of the euro figure. Chapter 1 develops the distinction.
The dossier is the defense. Not the absence of scrutiny, but the presence of paper. The audit file is built before the question is asked, not after. Chapter 3 walks the seven-layer corporate dossier.
The position is documented, not silent. Where the DGT has not resolved a point, the manual presents the two defensible positions, identifies the position retained by the author, and states the reasoning. Chapter 2 walks the withholding tax debate.
“The harbour master does not fear the ship with clean papers.”
— Salah Nomad
Inside the manual
- 1
The Framework
Why crypto payroll is a corporate tax problem. The three relationship types. MiCA, DAC8, and the corporate reporting perimeter.
- 2
The Mechanics
Withholding tax on crypto contractor payments. Cross-border VAT and the reverse charge. AEAT reporting across five models.
- 3
The Contracts
Three contract templates (standard, crypto-clause, hybrid). The Source of Funds annex for every contractor. The corporate audit file.
- 4
Case Files
Three Spanish SLs, three contractor configurations, with numbers preserved.
- 5
Glossary
35 terms.
- 6
Corporate Compliance Master Checklist
Printable on one page.
Show the other 2 chapters
- 7
Contract Templates Pack
Three contracts with SOF annexes, ready to adapt.
- 8
Sources and Verification Log
Primary sources and verification log.
Is it for you?
Built for
- CFOs, DAFs, and finance leads at Spanish SLs paying contractors in crypto
- Founders whose treasury is stablecoin-denominated but who need AEAT-compliant payroll
- Professionals who need the three contract templates and the SOF annex ready
Not for
- Freelancers — read the Autónomo Playbook instead
- Anyone seeking to hide crypto payroll from the AEAT
- Readers expecting the Playbook to replace a compliance officer
Written by Salah Nomad
Independent research with no commissions from any lawyer, agent or bank mentioned.