Field Manual · Revised October 2026
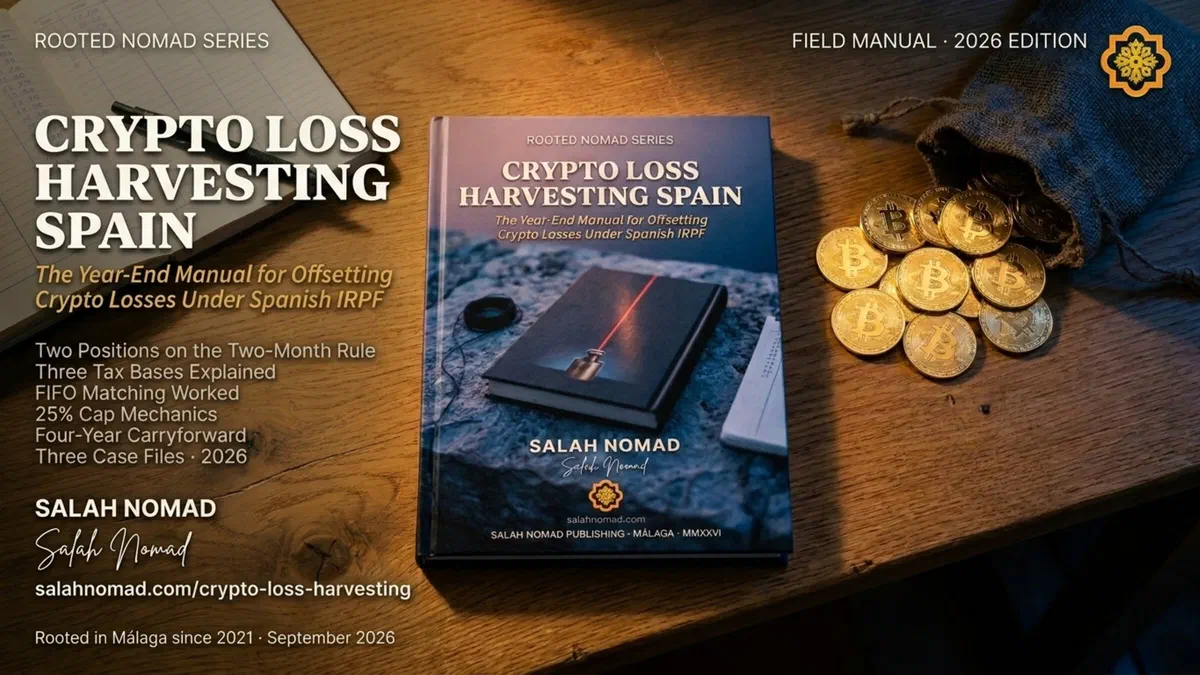
Crypto Loss Harvesting Spain
The Year-End Manual for Offsetting Crypto Losses Under Spanish IRPF
The Crypto Loss Harvesting manual documents Spanish IRPF loss offset for crypto portfolios. It covers the three-number calculation, 25% capital-income cap, four-year carryforward, FIFO lot matching, the anti-wash-sale debate, and three case files with exact numbers for year-end tax planning.
- Length
- 52 Pages
- Revised
- Oct 2026
- Format
- Delivery
- Instant link
Why this manual exists
Spain permits the deliberate realization of capital losses to offset gains. The strategy is legal. It has a name: compensación de pérdidas patrimoniales. It has constraints: the 25% cap on capital income, the four-year carryforward window, and the two-month anti-wash-sale rule.
What this guide solves
The three-number calculation. Before executing anything in December, compute: total realized capital gains, total positive capital income, total net loss available. The offset capacity is bounded by the first two, not by the third.
The anti-wash-sale rule — two positions. LIRPF art. 33.5.f denies losses when identical assets are reacquired within two months. Does it apply to crypto? Kointax says strictly no, by analogy. Legal Core Labs says yes by extension. Both positions presented with their legal basis.
The four-year carryforward. Unused losses carry forward under LIRPF art. 49, usable against future savings-base gains and capital income, subject to the same 25% cap. The carryforward is not lost — it is deferred.
“The harbour master does not fear the ship with clean papers.”
— Salah Nomad
Inside the manual
- 1
How to Use This Manual
Three steps, two categories, one carryforward.
- 2
The Spanish Loss Offset Framework
General vs savings base, offset order, 25% cap, four-year carryforward.
- 3
The Anti-Wash-Sale Rule
Two positions with legal basis; execution patterns for each.
- 4
The Year-End Execution
Cutoff, sequence, FIFO lot selection, documentation.
- 5
Case Files
Three taxpayers, three sizes, three outcomes.
- 6
Glossary
Twenty terms.
Show the other 1 chapters
- 7
Sources and Verification Log
Six regulatory sources, four practitioner sources.
Is it for you?
Built for
- Spanish tax residents with unrealized crypto losses at year-end
- Crypto holders planning the December offset execution
- Professionals who need the two anti-wash-sale positions documented
Not for
- Crypto holders with only realized gains and no losses to offset
- Anyone seeking to evade Spanish tax
- Readers expecting legal or tax advice
Written by Salah Nomad
Independent research with no commissions from any lawyer, agent or bank mentioned.